Zakat is carefully calculated and given on the day we receive income. The practical allowances help us carry out that duty; they do not create a general prepaid account or let us choose another payment day for convenience.
Zakat Is Defined by Calculation and Recurring Giving
A known net paycheck is an occasion to give, not merely an entry against money donated earlier. Rashad’s practical discussions address tiny dues that may be grouped for no more than a month, monthly net-income calculation, and a short group of small payments given ahead rather than held back. We read these as accommodations within the harvest-day duty. They do not create a separate payment schedule for ordinary paychecks.
Rashad Khalifa, God’s Messenger of the Covenant, states the rule directly: “You must give the zakat on the day of harvest.” He continues with the day we receive our money, taking out two and a half percent “no matter how small”, and giving it to the designated person (Quran Study 11/29, 15:50–16:11). This is the prescribed practice, not merely the safest option among interchangeable payment systems. The accommodations must be understood within that practice.
On this reading, a donation outside the rule and its applicable allowances is charity; it does not replace the zakat due when new income arrives. A gift can help someone without meeting that particular obligation. The distinction is between generosity and carrying out the defined duty, not between a generous person and an ungenerous one.
Paying on the Day of Harvest
[6:141] He is the One who established gardens, trellised and untrellised, and palm trees, and crops with different tastes, and olives, and pomegranate —fruits that are similar, yet dissimilar. Eat from their fruits, and give the due alms on the day of harvest,* and do not waste anything. He does not love the wasters.
Footnote: *6:141 Zakat charity is so important, the Most Merciful has restricted His mercy to those who give it (7:156). Yet, the corrupted Muslims have lost this most important commandment; they give Zakat only once a year. We see here that Zakat must be given away “On the day we receive income.” The proportion that came to us through Abraham is 2.5% of our net income.
The verse gives the day of harvest as the occasion for payment. Its footnote applies that command to the day we receive income and identifies the inherited proportion as 2.5% of net income. Appendix 15 brings the parts of the duty together:
Appendix 15, The Obligatory Charity: “Zakat must be carefully calculated and given away on a regular basis whenever we receive any income.”
This is a definition of the practice: carefully calculated AND given away, regularly, WHENEVER we receive income. “Regular” cannot be detached from “whenever” and reduced to any convenient recurring date. Giving once a year may be regular in ordinary speech, but it does not follow weekly or monthly receipts. One annual harvest with no other income is a different case because the actual receipt pattern is different. The footnote to [7:156] likewise requires giving upon receipt; retaining already purified savings does not itself create another due.
Rashad applies harvest directly to paychecks in New Messenger After 1400 Years, 26:18: when the paycheck comes, take out the proportion and give it to those in need. People who are hungry now cannot wait a year (26:47). In Essentials of Submission, 15:06, he describes a “continuous flow of money”. Regular giving is therefore part of the restored duty, not an optional benefit of doing it a particular way.
Our earlier discussion of the annual system opposed replacing this recurring duty with annual assessment. A proposal to pay ahead avoids one problem—holding back help—but it still has to preserve the defined practice. A balance showing enough money previously donated does not answer when and how the current income’s zakat is being fulfilled. Both how much is paid and how it is paid need support from the teaching.
The Messenger Clarifies the Duty; He Does Not Invent a Rival Law
[2:151] (Blessings) such as the sending of a messenger from among you to recite our revelations to you, purify you, teach you the scripture and wisdom, and to teach you what you never knew.
Teaching the scripture and wisdom is part of the messenger’s work. Explaining the scope and application of zakat is not the same as legislating against the Quran. Rashad restores a practice whose obligation the Quran commands and whose details came through Abraham. The Quran itself instructs Muhammad to follow Abraham’s religion ([16:123]).
[4:64] We did not send any messenger except to be obeyed in accordance with God’s will. Had they, when they wronged their souls, come to you and prayed to God for forgiveness, and the messenger prayed for their forgiveness, they would have found God Redeemer, Most Merciful.
Obedience to a messenger operates in accordance with God’s will. It cannot be separated from the messenger’s own obligation to follow revelation. The Quran states that boundary just as clearly:
[10:15] When our revelations are recited to them, those who do not expect to meet us say, “Bring a Quran* other than this, or change it!” Say, “I cannot possibly change it on my own. I simply follow what is revealed to me. I fear, if I disobey my Lord, the retribution of an awesome day.”
These verses belong together: the messenger teaches and is obeyed, while having no authority to replace God’s revelation with his own law. That is why the objection “an allowance outside the literal words of [6:141] would make Rashad a lawgiver” fails. Clarifying an inherited duty, its calculation and its practical application is not permission to abolish it. Nor may we enlarge an explanation until it displaces the command it explains.
Apply the same standard consistently. The number 2.5% is not written into [6:141], yet Rashad identifies “one quarter of one tenth” as what came through Abraham and tells us to take it from net income when received (22:42–22:55). He identifies 2.5% as the minimum and allows greater giving, including 50% (17:46–18:26). Appendix 15 says to deduct government taxes, and he confirms the net-income basis in the study (16:16–16:29). These are clarifications of the duty, not rival commandments.
The same reasoning applies to the permission to hold impractically tiny dues briefly and to the advice to advance a small group. Accepting those explanations does not require treating every imagined extension as another approved method. The consistent position is to accept both the messenger’s repeated rule and the accommodations in their stated settings. His explanation determines the scope; our preference for a different payment schedule does not.
Practical Accommodations Preserve the Duty
After the example of 25 cents due from a $10 receipt, Rashad allows an impractically small amount to accumulate for a couple of weeks or a month. He then says, “don’t go beyond a month” (27:09–27:19). The permission addresses an identified practical difficulty: handing over a tiny due. The money has already arrived, and the allowance briefly groups what must be given; it does not authorise routinely keeping a year’s zakat.
The limit here is a month, not a year, and it concerns holding dues after receipt. An advance is a different arrangement because the recipient receives the money sooner. The stated delay limit cannot simply be transplanted into the advance discussion as a universal prepayment deadline. Both accommodations still have to be read within the recurring duty they serve.
A separate recording addresses knowing the month’s net income: “it makes sense that we wait like a month, to know what our monthly income is”, followed by the paycheck or monthly income and calculation at month end (23:06–23:19). This concerns calculating the month’s actual income and giving its proportion. Variable receipts are an obvious practical case; a known net salary does not need another calculation period.
For an employee whose paycheck arrives as a known net amount, calculate its share and give when it arrives. I do not read the monthly calculation advice as permission to delay an already known salary merely for convenience. Nor does a readily distributable due create the tiny-payment problem addressed by the accumulation allowance.
The Advance Advice, in Its Actual Sequence
The advance exchange starts with the rule, not with an open invitation to choose any payment horizon. Rashad tells us to plan recipients ahead of payday, then give on receipt “no matter how small” (Quran Study 11/29, 15:26–16:11). The questioner raises grouping $1.50 or $2.50 amounts over two or three weeks into about $10. The concern is making small payments more useful to a family in need, and the answer addresses that concern.
| Passage | What happens in the exchange |
|---|---|
| 16:32–16:46 | The questioner recalls grouping small dues into a more useful amount. |
| 16:48–17:16 | Rashad recommends giving ahead to comply carefully and avoid leaving received income’s due unpaid; four amounts of $2.50 make $10. |
| 17:19–17:49 | The questioner returns to the small-sum grouping problem. The reply mentions $20, affordability and giving ahead. Some intervening speech overlaps. |
| 17:51–18:28 | A quiet timing objection is followed by discussion of the minimum, greater giving, 50% and the giver’s means. The objection’s exact words remain uncertain. |
| 18:32–18:38 | Rashad says the questioner created the problem by wanting a larger amount instead of a small gift. |
| 18:43–18:50 | He repeats the advance permission and the minimum percentage. |
“I would do it in advance then” answers the situation just raised: if the concern is grouping those small dues, give the group ahead (16:51). That way the wish to send a larger amount does not leave received income’s zakat unpaid. The warning about taking income into one’s pocket without its zakat out comes in this same answer (16:58–17:02). It explains his concern about owing the due; it does not cancel the advance advice that surrounds it.
“If you want to give in advance, if you want to give a big lump sum, that’s fine. The two and a half percent is a minimum.” (18:43–18:50)
The closing lump-sum approval remains within that exchange. Just before it, Rashad says the questioner wants a big amount instead of a small one and has therefore “created the problem” (18:35–18:45). He offers a way to accommodate that preference without leaving the received income’s due unpaid. The phrase is not a withdrawal of permission, and the intervening discussion of 50% does not turn the approved arrangement into forbidden conduct.
The scope follows the circumstances, not the questioner’s identity: another person facing the same small-dues grouping problem can apply the same advice. The allowance answers that practical problem. It does not make a separate gift before payday a substitute for the zakat on a later paycheck.
Source note: The recordings give the harvest-day instruction and the practical advice quoted here. The advance example gives four amounts, not an expressly declared four-week maximum or an express requirement that the initial payment happen on payday. The separate monthly-calculation passage mentions common paychecks; it does not say “irregular earners only”. Our application below explains how we read those cases within the recurring duty. Selected audio windows were checked with automatic transcription; that is not complete independent listening, and quiet or overlapping words remain uncertain.
A Contextual Allowance Is Not an Unlimited Exemption
For weekly pay, our practical application of the advance example is to combine the current small due with the next three weekly dues when giving alongside the current receipt: four amounts of $2.50 make $10. This illustrates the short grouping being discussed. It does not turn an unrelated donation on any earlier day into payment of later zakat.
Rashad’s example is four amounts of $2.50 making $10 (17:08–17:16). It addresses the wish to send a more useful small sum without holding back dues already received. Read that example as a solution to its stated problem, rather than an invitation to choose any number of future payments.
The controlling question is whether the proposed method still fulfils the duty clarified in Appendix 15. Giving a large amount on a large receipt, giving extra voluntarily, and claiming that one payment covers years of future zakat are different acts. Affordability may address extravagance, but it does not establish the last claim. An affluent person’s ability to fund years of projected dues does not remove “whenever we receive any income” from the definition.
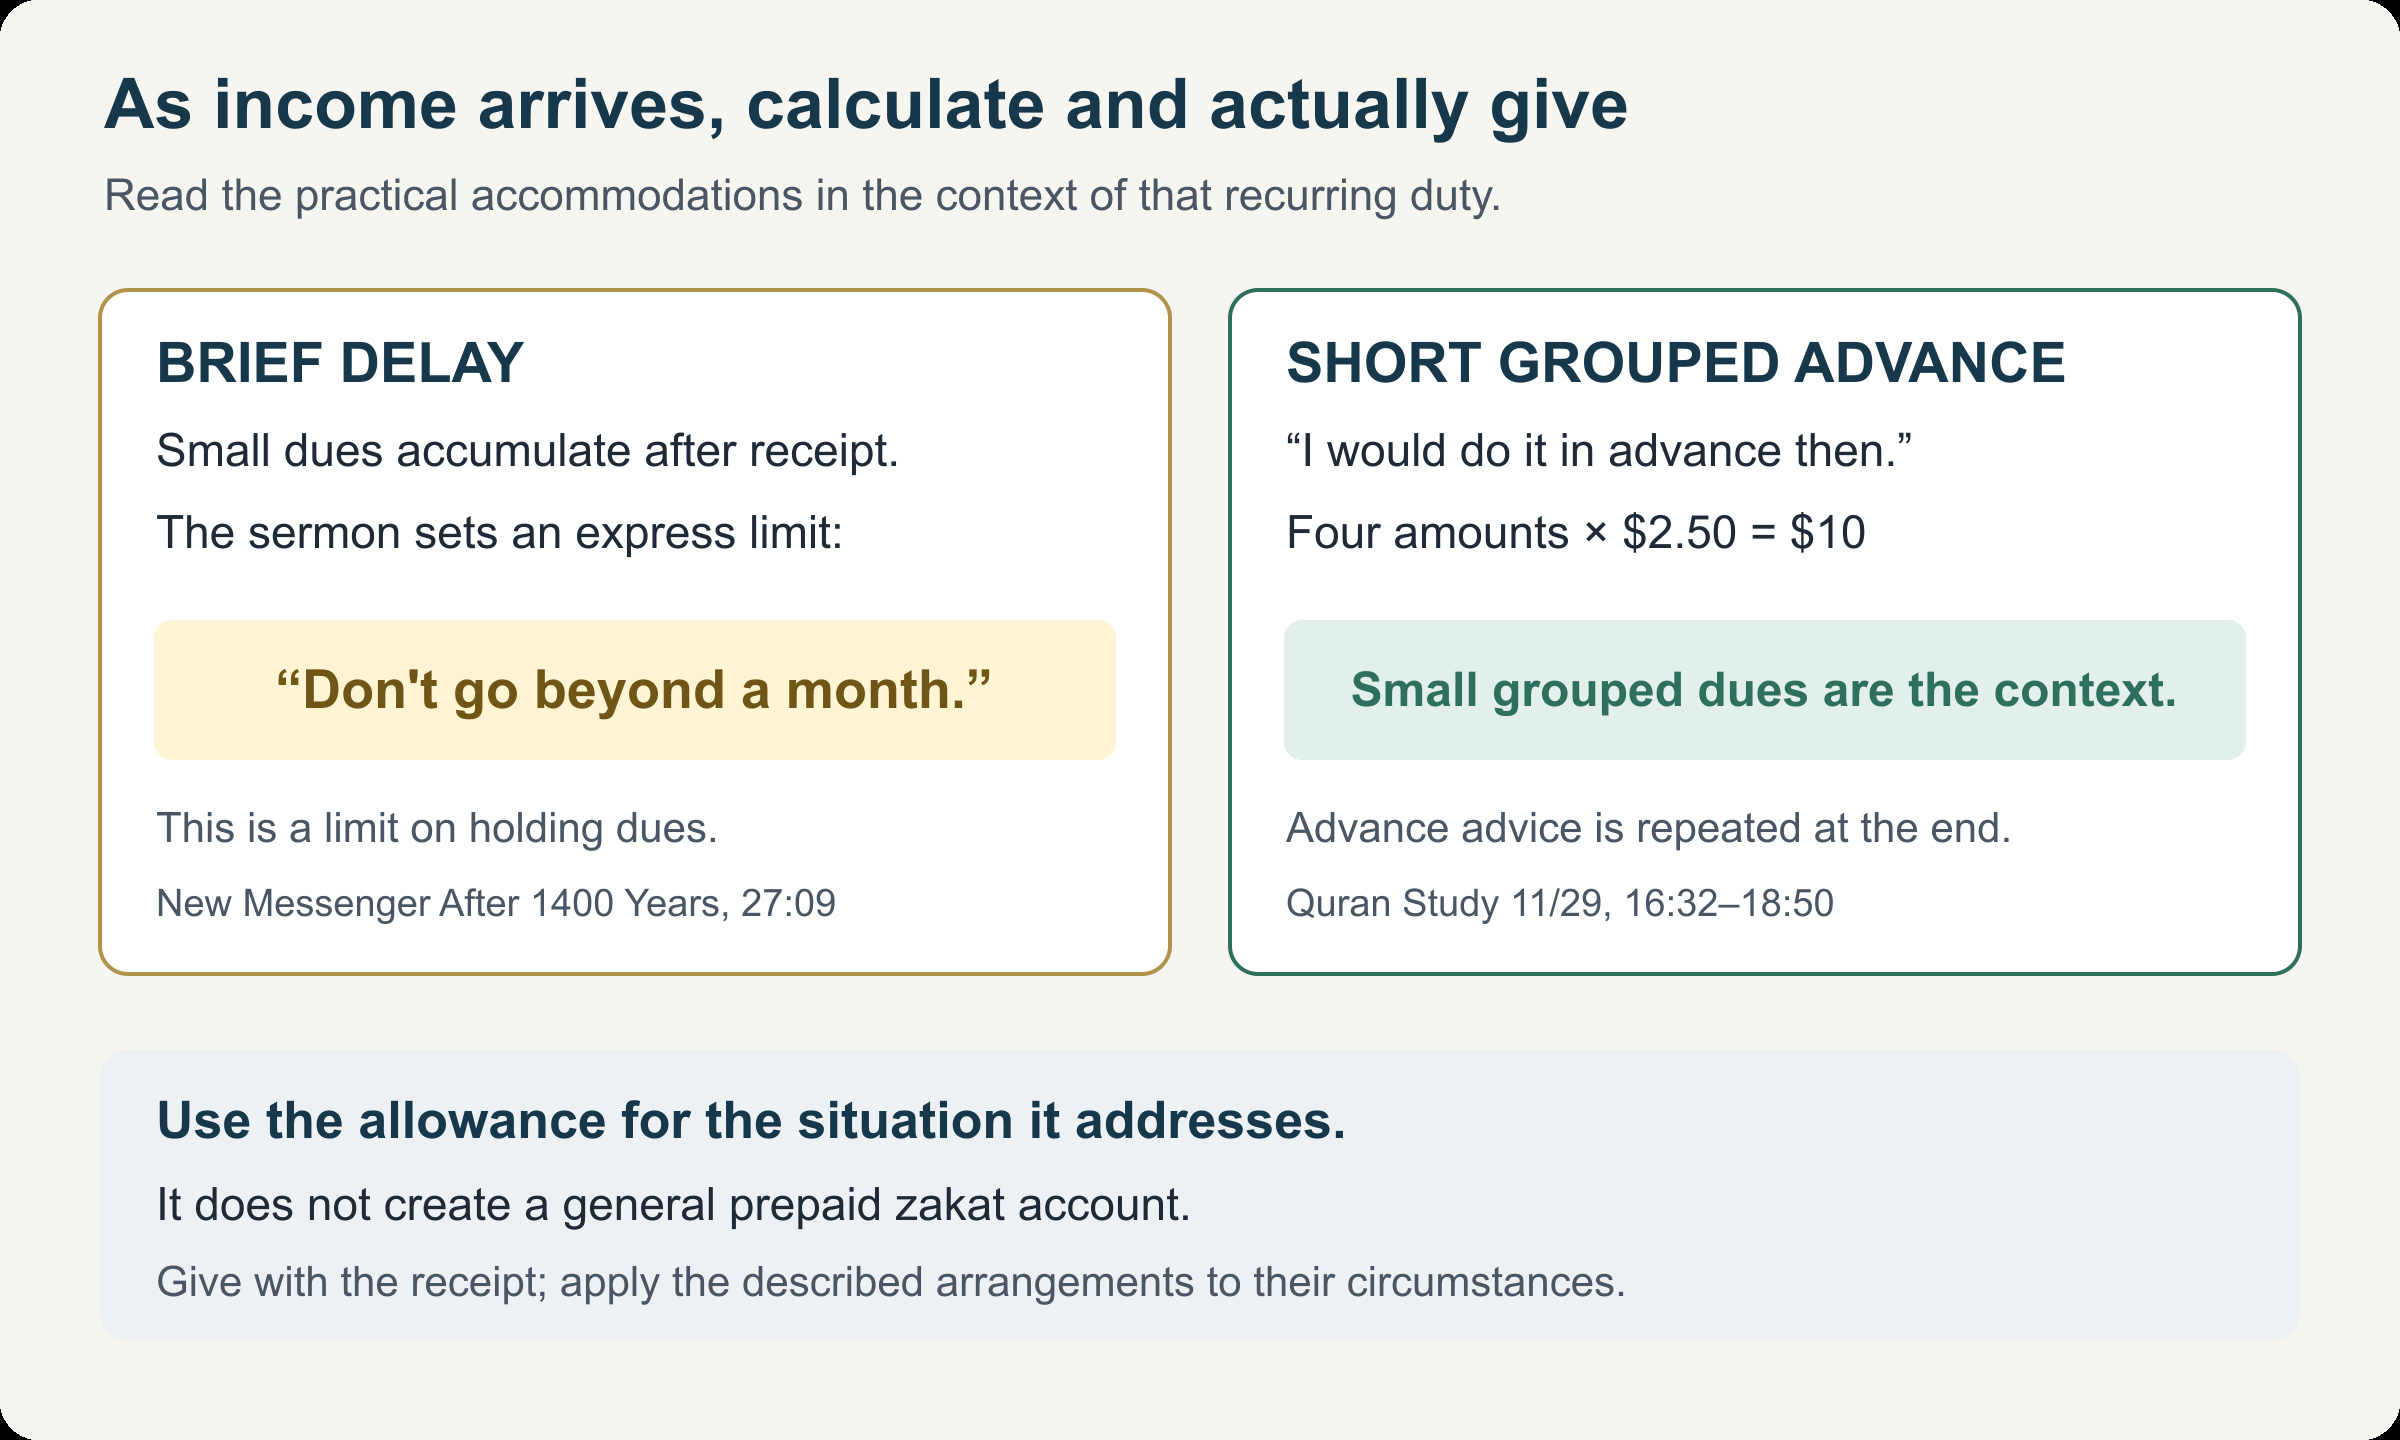
The rule governs the accommodation. The month limit applies to holding small dues. The advance answers the short grouping problem. In this article’s reading, neither creates a general prepaid account or makes unrelated earlier gifts payment of the next receipt’s zakat.
Practical Help and Fulfilment Are Different Questions
A grouped payment may be more useful to the recipient. That practical reason explains the advice; it does not authorise every scheme with a useful result. Fewer transfers, earlier help and convenient accounting can all be advantages without determining whether the arrangement fulfils the prescribed duty. The scope of a concession comes from the teaching, not from how broadly we can restate its possible benefits.
A gift can help someone without counting as the zakat due on a particular income. Appendix 15 itself distinguishes general institutional donations from zakat given through an institution specifically to help poor people. Good intent and a worthy institution do not erase the defined conditions. Timing and allocation likewise cannot be settled by the observation that the recipient benefited.
This is why a debate about practicality must not replace the question of permissibility. A large advance might be easy to afford and perfectly tracked; those facts still do not show that it substitutes for the required later giving. We should ask what in the teaching authorises that substitution. The absence of an announced maximum is not such an authorisation.
Does Giving One Day Early Automatically Count?
For an employee with a known net salary, give its zakat when it arrives. A separate gift the previous day, outside the small-payment arrangement, is additional charity in the reading argued here; it does not pay tomorrow’s zakat. The ordinary instruction is to calculate the current receipt’s share and give it that day.
Calling the gift “advance zakat” does not change that result. The accepted short grouping answers a particular giving problem; it is not permission to move a normal paycheck’s zakat to any date we prefer.
In the weekly application above, the grouped gift accompanies the current receipt and includes later small dues. Those covered dues were given ahead, so they do not need duplicate transfers on their later receipt days. That explains the allowance; it does not change the ordinary instruction to give with each receipt or turn a separate earlier gift into payment of new zakat.
Why an Unrelated Earlier Gift Does Not Replace Payday Zakat
This criticism concerns gifts outside the practical arrangements just discussed. If we treat such a gift as payment and give nothing when new income arrives, the current obligation has been left unpaid. The problem is not that the gift helped too soon; it is that a different act has been used to replace the duty.
First, it turns charity into zakat. God defined zakat and the messenger explained it: a set share of our net income, calculated carefully and given away when the income arrives. A gift outside that rule is good charity, but it is still charity. Calling it zakat gives a duty a new meaning that God never gave it. This is exactly what [9:31] and [42:21] condemn: “They have set up their religious leaders and scholars as lords, instead of God,” and “They follow idols who decree for them religious laws never authorized by God.” Writing our own version of zakat, and then calling it God’s, is writing a religious law that He never authorized.
Second, the real zakat is still unpaid. The zakat on that income is already owed, and God says to pay it on the day of harvest, the day the income arrives. The early gift was a different act, so that amount has not been paid. It stays unpaid, and because the giver believes it is settled, nobody notices and nobody fixes it. The next income then adds another unpaid due on top. Rashad warned about taking income into our pocket without taking out its zakat, saying that “apparently it is a gross crime” (Quran Study 11/29, 16:58–17:08).
Third, it teaches a different practice. In [6:141] God says to “give the due alms on the day of harvest.” On the reading argued here, telling an ordinary wage earner that an unrelated earlier gift pays the next paycheck’s zakat leads them to leave that due unpaid. That is why the classification matters: a mistaken allocation can become a mistaken teaching.
The grouped advance that Rashad approved remains an allowance within this account. His warning occurs inside that answer, so it cannot be used to condemn the arrangement he recommended. The criticism here concerns replacing the ordinary duty with a different practice. It does not decide what any individual knew, intended or owes from past allocations.
Actual Income, Calculation and Conscious Intention
In the college-support example, Rashad explains that helping a sister can count, but the giver must calculate the proportion: “So I receive this income, 2.5% is this much”, then give it and add more if desired (Quran Study 1-11-89, 50:32–50:44). He also rejects the idea that the classification happens automatically: “you have to have the intention”, and be aware that a proportion of income is being given as the obligatory charity (50:49–51:14).
So both the calculation and the intention matter. Helping someone does not automatically count as paying zakat, and deciding in our heads that a gift will cover future zakat does not make it so. The passage does not require us to tell the recipient that the money is zakat, and the Quran praises giving charity privately in [2:271].
Conscious intention identifies the act we mean to perform; it does not rewrite its conditions. Intending a gift as six years of zakat cannot by itself convert the recurring duty into a single event. Rashad’s instruction begins with receiving the income and calculating its proportion. Our intention should carry out that instruction, including an accommodation where it applies.
Keeping records helps in the same way. Notes help us work out our net income and avoid mistakes, especially when money comes from more than one source. They can also check an approved advance against the income that actually arrives. But writing a payment down only records it; it cannot make a payment count as zakat when the teaching does not allow it.
What the Harvest Wording Establishes
The relevant Arabic in [6:141] ties the payment to the harvest:
كُلُوا مِن ثَمَرِهِۦٓ إِذَآ أَثْمَرَ وَءَاتُوا حَقَّهُۥ يَوْمَ حَصَادِهِۦ
The canonical English above says: “Eat from their fruits, and give the due alms on the day of harvest”. In the Arabic, حَقَّهُۥ and حَصَادِهِۦ mean, in a close editorial gloss, “its due” and “its harvest”. What is owed from the produce is its due, and the command is to pay that due on the day the produce is harvested. That is why Rashad applies it to the day we receive income.
Rashad’s spoken explanation makes the connection to the particular harvest explicit. He refers to the zakat charity for “that crop” and says to give it “on the day of harvest” (22:08–22:15). He then applies harvest to paychecks and instructs us to take 2.5% of net income when we receive it (22:34–23:02). The zakat comes from the crop being harvested, or the income being received, and it is paid on that day. A past donation cannot simply be assumed to cover it. This identifies which income the payment must fulfil; it does not require handing over the very same banknotes or erase the grouped-advance concession explained above.
The payment belongs to the crop being harvested or the income being received. That is the rule we apply to ordinary paychecks. The grouped advance addresses the different practical problem already described: a wish to send a larger small sum without holding back zakat. It does not turn knowing a future payday into general permission to stop giving when that payday arrives.
[9:103] Take from their money a charity to purify them and sanctify them. And encourage them, for your encouragement reassures them. God is Hearer, Omniscient.
The Quran here speaks of charity purifying the people. Rashad also describes purifying income, including the example of being paid despite sleeping on the job (sermon, 27:32–28:08). His separate example of money purified once concerns a loan from funds on which the charity has already been given (Quran Study 7/27/89, 29:03–29:20). It prevents repeatedly assessing the same returned principal merely because it comes back; it does not require donating the physical banknotes from the newly received sum. The question is which income’s due has been paid. Purification does not remove the timing instruction or its applicable allowances.
What matters is the link between the income, the amount calculated on it and the giving that follows. We do not need a theory about which particular coins are handed over. And the word “purification” does not turn a past donation into payment for future zakat. The messenger’s actual instructions tell us how to apply it: give on the day the income arrives, and pay ahead only in the situation he addressed.
Annual Savings and Annual Advance Are Not the Same Arrangement
Rashad criticises paying once a year on savings in The Great Debate, 1:00:14, and contrasts the annual savings calculation with payment on receipt in Quran Study 1-11-89, 15:30–18:44. A rule assessing accumulated savings after a holding period is different from a proposal to estimate the dues on next year’s income. The two can both involve an annual date without having the same assessment base or the same defects.
A traditional report illustrates why the expression “in advance” needs context. In Tirmidhi 678, the English source presents al-Abbas asking to pay before the due time, with a parenthetical explanation referring to a whole year of possession. The cited page marks this route weak. We show the report to identify the argument being made in that literature, not to adopt it as authority for our duty.
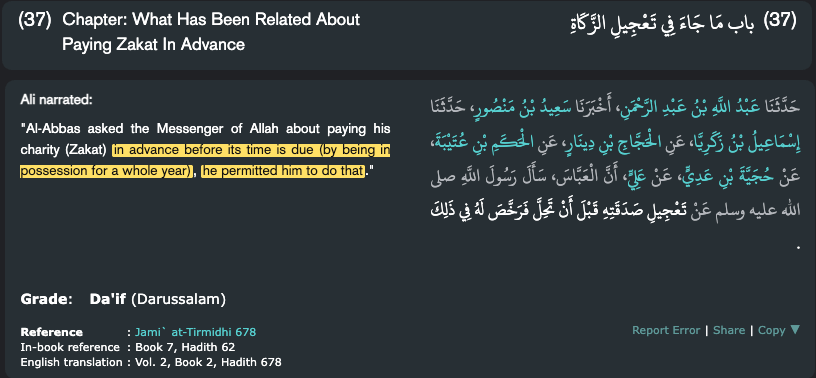
Jami` at-Tirmidhi 678, narrated from Ali. The page’s English translation includes the possession-period explanation and displays the grade Da’if (Darussalam). Yellow highlighting is added.
IslamQA’s answer 160574 gives a concrete salary-savings method: choose an annual date after reaching the threshold and assess all current savings, including recently saved salary. The later savings are treated as paid ahead of their own holding-period dates. The answer quotes Ibn ‘Uthaymeen approving “one or two years in advance”. This example concerns money already saved, rather than next year’s earnings.
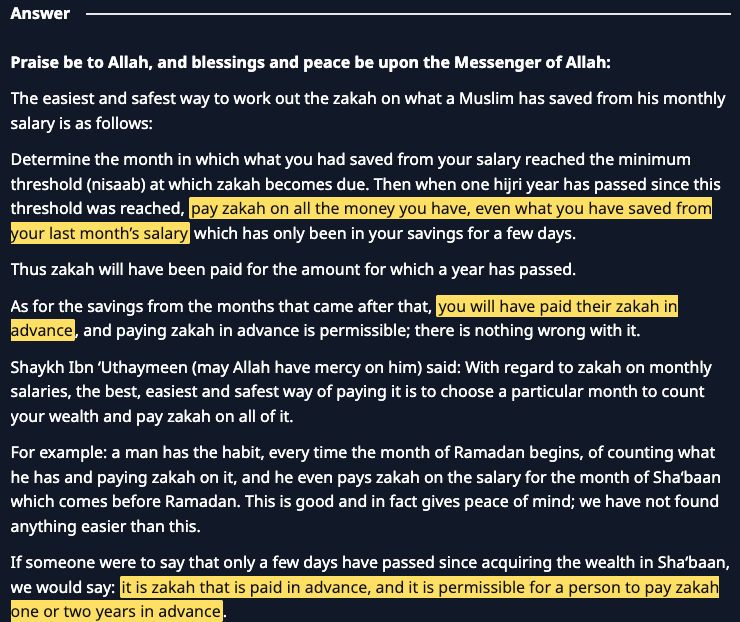
IslamQA, “How should he pay zakah on his savings from his monthly salary?” (7 July 2020). The excerpt shows the annual savings calculation and the advance language in its context. Yellow highlighting is added.
Nor is it accurate to say every Sunni pays every receipt one year late. Jordan’s General Iftaa Department, ruling 3092 (14 July 2015), treats a lunar holding year as a condition for the saved monetary wealth discussed, then requires payment when that period ends. Payment at that due date is not overdue under that rule. Egypt’s Dar al-Ifta, “Paying zakat on my salary” (23 February 2015), permits intended advance instalments as salary arrives, reconciled against annual liability. Jordan’s official Zakat Fund separately gives harvest-time payment for qualifying crops. These are descriptions of institutional rules, not a claim about every person’s conduct.
“In arrears” may mean payment after a period rather than payment already overdue. Neither meaning accurately captures every Sunni arrangement. Rashad’s criticism is broader: his January study also objects to assessing the same already-purified savings again the following year (18:13). The dispute concerns the assessment base, holding period, threshold, repeated assessment and frequency—not merely missing a date that both systems accept. Traditional advance rulings therefore cannot be imported as authority for the restored receipt-based duty.
The question about keeping track of a year follows the explanation of immediate giving and purification (sermon, 28:08–28:11). That context does not identify annual tax settlement as the problem being discussed. It reinforces his criticism of the annual arrangement; it is not an express answer about a monitored payment made a year early.
An annual advance may provide help sooner and avoid repeatedly assessing savings, but those benefits do not change the timing instruction. I therefore reject a general prepaid balance as a way of paying zakat. Outside the practical arrangements discussed, an earlier donation remains charity and the zakat is still paid when the income arrives.
Keeping Perfect Track Does Not Change the Rule
A ledger can show that a donation was made and that its amount matches later calculations. It cannot decide whether that donation meets the prescribed duty. Eligible recipients, sincere intention and accurate arithmetic all matter, but none makes an unrelated earlier gift payment of a later paycheck’s zakat.
The ordinary case makes the point without a lifetime example: a salary arrives today. Under the rule argued here, its zakat is calculated and given today, unless the payment belongs to one of the practical arrangements described. A general credit balance is not another such arrangement.
Rashad compares planning the payment to planning the afternoon Contact Prayer (15:37–15:45). Planning prepares us to perform the duty at its occasion. It does not replace that occasion with a date of our own choosing.
Read the Teachings Together
Read the repeated harvest-day instruction alongside the small-payment and monthly-calculation discussions. They explain how to carry out the duty in practical circumstances. They are not competing systems from which an ordinary wage earner chooses a preferred giving schedule.
The foundation is [6:141], Appendix 15 and Rashad’s repeated instruction to calculate and give when income arrives. Calculation and actual giving belong together. An eventual total does not replace that continuing act of worship.
Receipt-based giving already accommodates different livelihoods. A farmer’s harvest, an employee’s paycheck and income from trading or sales do not arrive on identical schedules; Rashad names trading, investments and sales in the January study (15:54–16:09). “Whenever” follows those actual receipts. It does not impose a fixed monthly charge when there has been no new income, and it does not let a regular wage earner disregard the receipt that has occurred.
For Regular Paychecks, Make Giving Part of Payday
[2:215] They ask you about giving: say, “The charity you give shall go to the parents, the relatives, the orphans, the poor, and the traveling alien.” Any good you do, God is fully aware thereof.
For a monthly employee paid a known net salary, the ordinary practice is clear: prepare the recipients, calculate 2.5% and give it when the paycheck arrives. Do the same with additional income when it arrives. Appendix 15 deducts government taxes, but not debts, mortgages or living expenses. This defines net income for the calculation; it does not require waiting for the government’s final annual tax settlement before giving.
- Known net paycheck: calculate its due and give on receipt. Prepare the recipients beforehand.
- Impractically tiny dues: use the brief accumulation allowance; do not hold them beyond the stated month.
- Monthly calculation: establish the month’s actual net income and give its share. Do not use the calculation period merely to delay a known salary.
- Short grouped advance: apply the solution to the small-payment situation it addresses. Our weekly example gives the current due and three later small dues alongside the current receipt.
- Separate gifts: do not deduct an unrelated earlier donation from later zakat simply because it was given before the money arrived.
- Extra generosity: give more when you can afford it and people need it. Giving more today does not by itself pay the next receipt’s zakat.
If an advance has already been made in good faith, its actual circumstances and allocation need examination; this article does not invent an automatic requirement to pay every amount twice. For practice going forward, keep the receipt-based duty in view and use the accommodations for the situations they address. A normal, calculable paycheck supplies the occasion to give. It is not a reason to redesign zakat as a prepaid account.
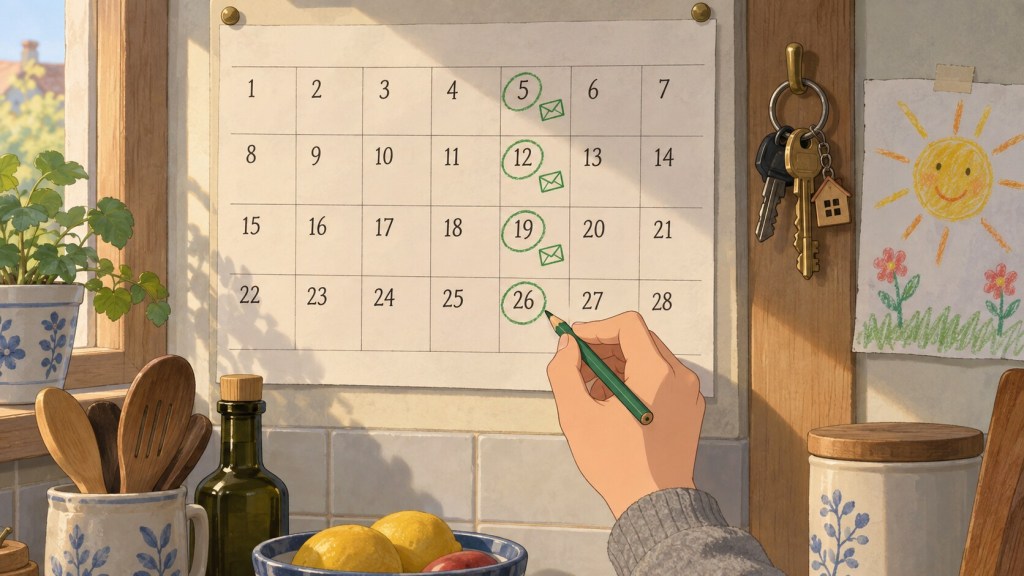
An illustration of regular giving alongside weekly receipts. The four marked dates are a household example, not an advance-payment ceiling.
Be Generous, and Be Accurate About God’s Requirement
[25:67] When they give, they are neither extravagant, nor stingy; they give in moderation.
The Quran’s praise of charity is not permission to ignore moderation or manner. [17:29] warns against both stinginess and foolish expenditure; [2:263] and [2:264] warn against insult, reproach and display. A larger or earlier payment is not automatically a universal measure of greater righteousness. Needs, means, intention and conduct still matter.
[9:79] Those who criticize the generous believers for giving too much, and ridicule the poor believers for giving too little, God despises them. They have incurred a painful retribution.
This warning rules out contempt for generous believers and ridicule of those who can give little. It does not stop us from examining a claim that one donation pays off years of future zakat. We can value the help while rejecting an interpretation that replaces the commanded giving. That is a judgment about the method, not a declaration of another person’s final standing before God.
Zakat is carefully calculated and given away on a regular basis whenever we receive income. The messenger clarified that duty, including its proportion, net-income basis, recipients and practical accommodations. Honour those explanations together. As God continues to provide, continue the prescribed giving; a concession that helps fulfil the rule is not a licence to replace it.


Leave a Reply